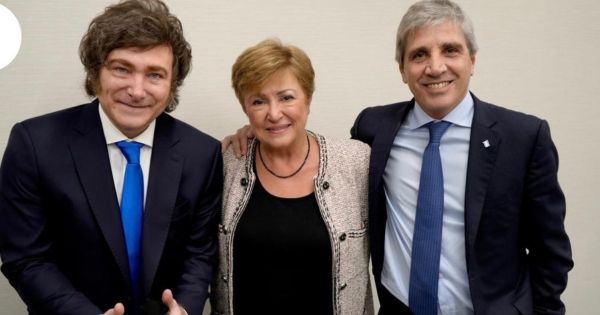
A technical delegation from the International Monetary Fund (IMF) will arrive in Argentina next week to conduct the third review of the current program agreed with Javier Milei’s government. According to Crónica, officials will arrive on Monday, September 21, ahead of a debt maturity with the organization.
The mission will not be received by Economy Minister Luis Caputo, who will travel to New York with President Milei to participate in the United Nations (UN) meetings.
Exchange rate targets: overcompliance in foreign currency purchases
On the exchange rate front, the Central Bank of Argentina (BCRA) exceeded the annual foreign currency purchase target set at 10 billion dollars. According to Crónica, the entity purchased more than 14.2 billion, representing an overcompliance of more than 4.2 billion compared to what was agreed.
As for the reserve accumulation target for 2026, set at 8 billion dollars, estimates from the consulting firm Analytica indicate that the BCRA is above the target, reaching 9 billion. This figure comes from a private estimate and not from an official confirmation by the organization.
The fiscal front: the main complication
Public accounts appear as the most difficult area for the agreement’s targets. For this year, the program requires a primary surplus of 1.4% of Gross Domestic Product (GDP). However, during the first half, the Government obtained 0.6% of GDP, falling below the semi-annual target of 0.7% of GDP.
To try to shield the surplus, authorities made commitments during the second review, such as postponing the implementation of the Labor Assistance Fund (FAL) until November 1, increasing collection through specific taxes, and deepening the targeting of transport subsidies.
Debt maturities and projected payments
Crónica notes that Argentina will face a maturity with the IMF on Friday, September 25, for 803 million dollars. Then there will be a payment of 840 million dollars for early November and another of 344 million for December.
The IMF’s primary source, an official TSV download of projected payments updated as of June 30, 2026, presents figures in Special Drawing Rights (SDR). According to that document, on September 25, 2026, a GRA Repurchase (EFF) payment of 583,333,333 SDR is due. For November 1, 2026, several concepts are listed: GRA Time Based Surcharge (61,921,353 SDR), Net SDR Charges (35,709,241 SDR), GRA Level Based Surcharge (165,123,609 SDR), and GRA Basic Charges (363,827,602 SDR). On December 24, 2026, a GRA Repurchase (EFF) of 250,000,000 SDR is listed.
It is important to note that Crónica’s figures are expressed in dollars, while the IMF’s are in SDR. It is not possible to convert currencies without an SDR-to-dollar exchange rate with an exact date, data that is not included in the supplied material. Therefore, the original units are preserved and no direct equivalence is established between the two sources.
Data comparison: maturities and targets
| Concept | Source 1 (Crónica) | Source 2 (IMF, official TSV) | Observation |
|---|---|---|---|
| September 25 maturity | 803 million dollars | 583,333,333 SDR (GRA Repurchase EFF) | Different units; not convertible without SDR/dollar exchange rate. |
| Early November payment | 840 million dollars | Sum of concepts: 61,921,353 + 35,709,241 + 165,123,609 + 363,827,602 = 626,581,805 SDR | Source 1 mentions a global payment; Source 2 breaks down concepts. |
| December payment | 344 million dollars | 250,000,000 SDR (GRA Repurchase EFF, Dec 24, 2026) | Different units; not convertible without exchange rate. |
| 2025 foreign currency purchase target | 10 billion dollars (annual guideline) | Not in Source 2 | Only reported by Crónica. |
| Actual BCRA purchases | More than 14.2 billion dollars | Not in Source 2 | Overcompliance of 4.2 billion according to Crónica. |
| 2026 reserve target | 8 billion dollars | Not in Source 2 | Analytica estimate: 9 billion. |
| Annual primary surplus | 1.4% of GDP | Not in Source 2 | Program target. |
| Semi-annual primary surplus | 0.6% of GDP (semi-annual target 0.7%) | Not in Source 2 | Shortfall relative to semi-annual target. |
Methodological note: The table contrasts data from two sources with different units. Source 1 (Crónica) expresses amounts in dollars and percentages of GDP. Source 2 (IMF) expresses amounts in SDR. No conversion is performed because the SDR/dollar exchange rate with an exact date is not available in the material. Source 2 figures correspond to projected payments as of June 30, 2026. The sum of concepts for November 2026 was calculated from the values listed in the official TSV. This operation is a simple arithmetic sum: 61,921,353 + 35,709,241 + 165,123,609 + 363,827,602 = 626,581,805 SDR. Document: Projected Payments to the IMF as of June 30, 2026. Organization and date: IMF, updated as of June 30, 2026. Unit: SDR. Values used: the four concepts listed for November 1, 2026. Operation: sum.
What data or decision to follow
The development of the third IMF review will reveal whether the organization validates the overcompliance in the exchange rate target and how it evaluates the semi-annual fiscal performance. It will also be relevant to observe whether the amounts and dates of debt maturities are confirmed, and whether the Government maintains the commitments made in the second review, such as the postponement of the FAL and changes in transport subsidies. The evolution of reserves and the primary surplus in the second half will be key indicators to anticipate the outcome of the review.
Fuentes consultadas
- Crónica
- Fondo Monetario Internacional Fuente primaria
El Sereno contrastó las fuentes enlazadas y añadió contexto, comparación o análisis documental. Las fuentes primarias están identificadas. La nota no se presenta como investigación de campo ni como entrevista propia, salvo indicación expresa.


Comentarios