Two independent sources address different issues. A news article describes programs for manufacturing spare parts for classic cars. An official statement from the Ministry of Economy details proposed changes to the Tax Innocence regime. There is no causal relationship between the two materials.
Spare parts programs for out-of-production models
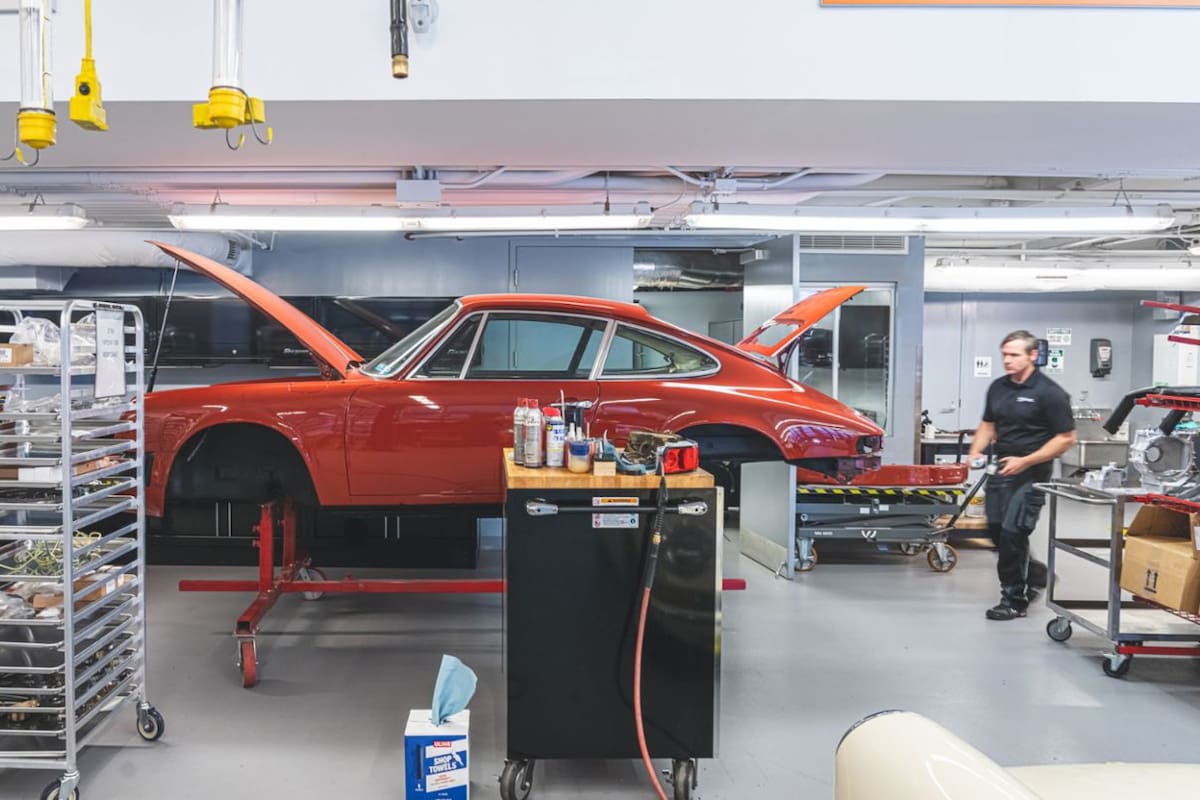
The La Nación article —a secondary source— mentions that Toyota maintains the GR Heritage Parts program, started in 2020, with a catalog exceeding 300 components and covering eight model families, including the 2000GT, Supra A70 and A80, Corolla Levin and Sprinter Trueno AE86, and the 40, 60, 70, and 80 series of the Land Cruiser. Earlier this month, according to the same article, the company opened orders for new components of the 4A-GE engine, including cylinder head and block.
Nissan, through NISMO Heritage, focuses its strategy on the R32, R33, and R34 generations of the Skyline GT-R. This year it added injectors, turbo gaskets, sensors, suspension components, and the front drive shaft of the R32. In several cases, according to the source, the parts were remanufactured with the same original supplier. It also used 3D printing to reproduce fuel system clips.
Porsche Classic currently has information and supply for more than 80,000 original parts for classic models, from historic vehicles to relatively recent generations. The article notes that a reproduced part is not necessarily an identical copy to the one manufactured decades ago, but it maintains function, quality, and original replacement guarantee.
The challenge these programs face, according to the source, is that a modern vehicle is manufactured in hundreds of thousands of units and allows amortizing molds and dies, while a part for a classic has reduced demand. Companies acknowledge they must work with suppliers, adopt modern technologies, and find ways to manufacture in small volumes sustainably.
Proposed changes to the Tax Innocence regime
The Ministry of Economy statement —a primary source— reports that Minister Luis Caputo and the Legal and Technical Secretary of the Presidency, María Ibarzabal Murphy, announced modifications to the Tax Innocence Bill. At a press conference, tax experts Sonia Becherman, Liban Kusa, and Ricardo Paolina answered questions about the main changes.
Caputo stated that «the spirit of the law does not change at all» and that the goal remains that savings can be formalized in the banking system without penalty. He explained that the decision to push for a new law arose after receiving observations from tax advisors on the previously approved regulations. He mentioned that they set up a working group with tax experts to clarify issues and reassure citizens.
The minister emphasized that the initiative seeks to respond to a process of growing informality generated by years of high tax pressure, fiscal deficit, monetary emission, inflation, and exchange restrictions. He noted that currently dollar deposits in the financial system reach record levels close to 40 billion dollars, but there is an amount more than four times that in savings outside the banking circuit.
The first proposed change eliminates the current conditions for entering the simplified sworn earnings declaration system. Today the law simultaneously requires: income not exceeding one billion pesos annually, total assets not exceeding ten billion pesos, and not qualifying as a «Large Taxpayer» under ARCA rules. The bill eliminates those conditions and opens the regime to all resident individuals and undivided estates, regardless of assets or income, with an exception for «Large Taxpayers.» These may adhere to the simplified modality, but do not enjoy presumptions, liberating effects, or other benefits.
The second change modifies the threshold to break the presumption of accuracy. Today, if ARCA’s challenge results in an increase of 15% or more over what was declared, the presumption automatically falls. The bill introduces a minimum threshold: even if 15% is exceeded, the presumption is not broken if the nominal difference claimed does not reach the equivalent of 5% of the evasion amount provided in Art. 1 of the Tax Penal Law. In concrete numbers, if the difference does not exceed five million pesos, the presumption is maintained.
The third change allows that, if ARCA detects a significant discrepancy, the taxpayer can file an amended sworn declaration and pay the difference plus interest within a period of up to 15 business days from notification of the official determination.
The fourth change provides an additional tool: the presumption of accuracy is fully restored and ARCA is obligated to refund the contributions paid with interest within a period no greater than 45 business days from notification of the final resolution.
Differences and limits between sources
The two sources do not share topic, actors, or period. The La Nación article is a secondary source that describes manufacturing programs for classic car parts, without citing original documents from the automakers. The Ministry of Economy statement is a primary source that details proposed changes to a tax regime, with direct quotes from the minister and tax experts.
It is not possible to calculate differences, percentages, or equivalences between the two sources because they measure different phenomena. Within the official statement, there are quantitative data: dollar deposits close to 40 billion and savings outside the system more than four times that amount. The source does not specify the exact date of those values or the exchange rate used, so they are kept in dollars and pesos according to the original text.
Document: Ministry of Economy statement. Agency and date: Ministry of Economy, press conference this Wednesday (exact date not recorded in the material). Unit: millions of dollars and multiples. Values used: deposits close to 40 billion dollars; savings outside the circuit more than four times that amount. Operation: multiplicative relationship mentioned by the source, not calculated by this outlet.
What’s next
It is advisable to follow the evolution of the Tax Innocence bill in Congress, particularly the 15% and 5% thresholds and the 15 and 45 business day deadlines, because they define taxpayer protection. Meanwhile, for the spare parts programs, it remains to be seen whether Toyota, Nissan, and Porsche expand catalogs or modify sales conditions, although the source does not indicate precise dates for those announcements.
- Immediate effects: the article describes programs already active; the statement announces proposed changes that still must be approved.
- Conditioned effects: the opening of the regime to all taxpayers and the new thresholds depend on legislative approval.
- Uncertain effects: there is no data on volume of parts sold or on the expected revenue impact of the tax changes.
Fuentes consultadas
- LA NACION
- Argentina.gob.ar Fuente primaria
El Sereno contrastó las fuentes enlazadas y añadió contexto, comparación o análisis documental. Las fuentes primarias están identificadas. La nota no se presenta como investigación de campo ni como entrevista propia, salvo indicación expresa.
Comentarios